
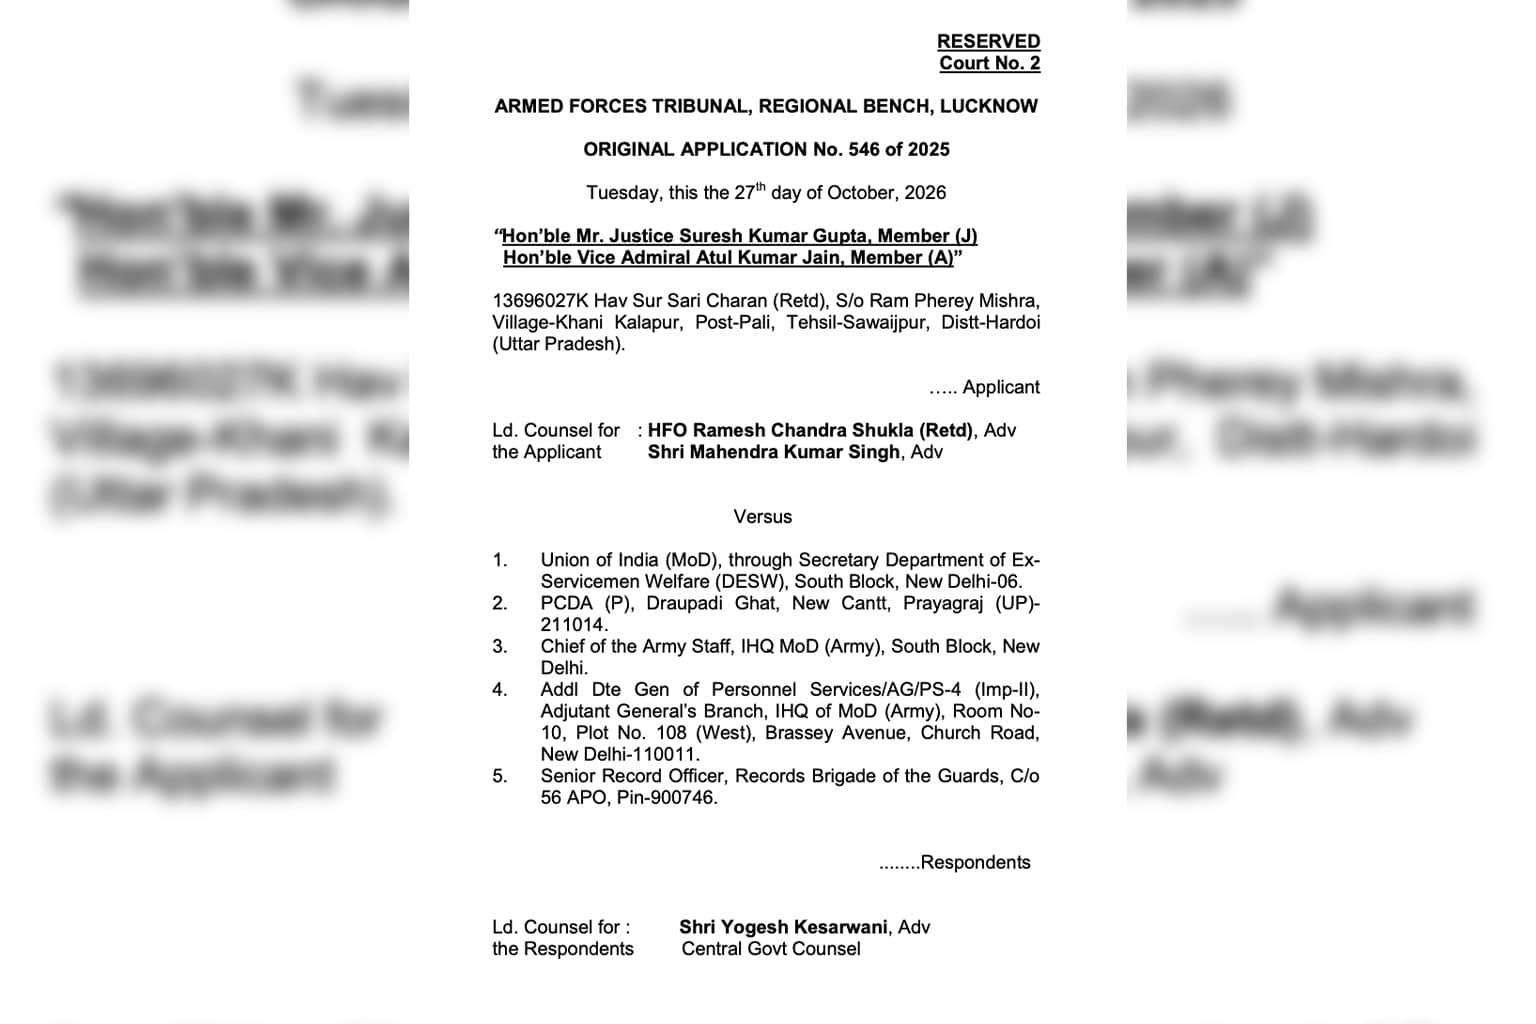
Download the Court Judgement
What happens when a pension department recovers an incorrect payment but continues deducting money from the pensioner’s account afterward?
A recent Armed Forces Tribunal (AFT) judgment from Lucknow highlights why pensioners should carefully check their recovery records.
On 27 October 2026, the Tribunal directed payment of 6% annual interest and ₹25,000 in compensatory costs to a retired Army Havildar who faced additional pension deductions after an erroneous commutation payment had already been recovered.
The decision in O.A. No. 546/2025 offers an important lesson about pension-account
How can one pension payment lead to two recoveries?
The dispute involved Havildar Sur Sari Charan (Retd.), who had been receiving pension following his discharge from the Army in May 2016.
On 13 June 2024, an amount of ₹12,95,325 was mistakenly deposited into his bank account as the commuted value of pension. The same benefit had already been paid earlier.
Instead of retaining the additional money, the veteran informed the authorities by email on 16 June 2024.
The entire erroneous payment was subsequently recovered from his bank account on 31 July 2024.
The problem arose when further deductions began from his regular pension in November 2024, even though the original overpayment had already been recovered.
This distinction became central to the Tribunal’s decision.
What did the pensioner do before approaching the tribunal?
The judgment records that the veteran contacted the authorities and pursued the matter through official correspondence and grievances.
His Army Records office also wrote to the concerned pension authorities seeking examination of the additional recovery and refund of the excess deductions.
Despite these efforts, the dispute continued.
The pensioner eventually approached the Armed Forces Tribunal, challenging the deductions and seeking financial relief.
An important development occurred on 2 September 2025, when the Tribunal ordered the recovery to stop.
By the final hearing, the amounts additionally deducted from his pension had been refunded. The remaining dispute concerned interest and compensation.
AFT Lucknow Judgment: What relief was actually granted?
The Tribunal examined the payment history and accepted that the original ₹12,95,325 overpayment had already been recovered.
It then considered the financial consequences of the subsequent deductions.
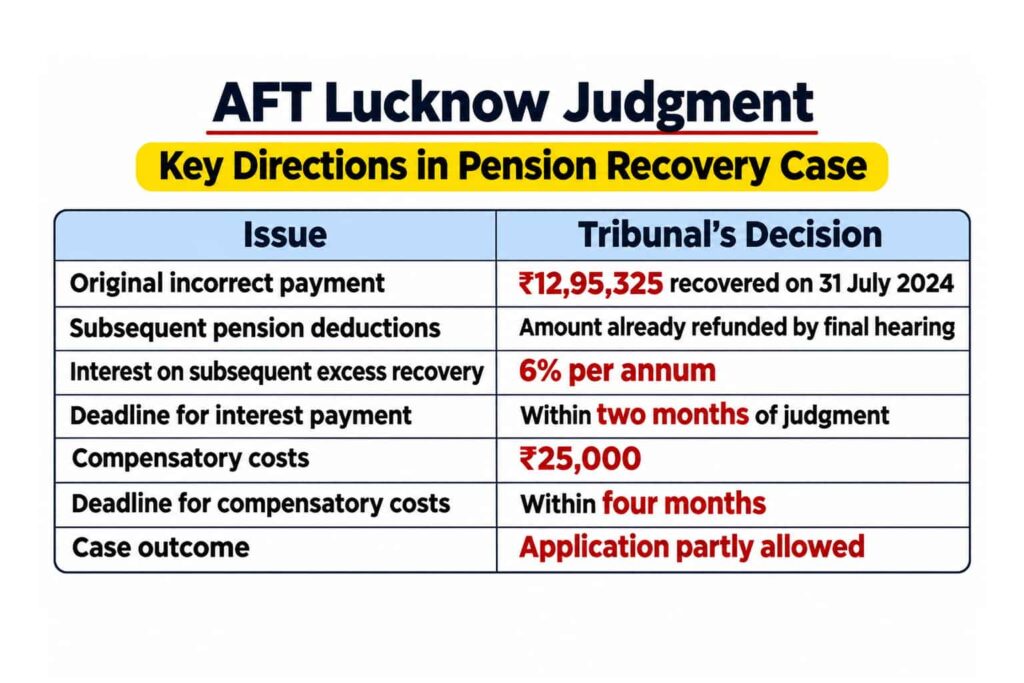
The Tribunal also provided for an additional 6% annual interest consequence in the event of default in paying the ordered interest.
It referred to the Supreme Court’s decision in Ramrameshwari Devi v. Nirmala Devi while considering compensation for unnecessary litigation.
The ₹25,000 award was compensatory costs arising from the litigation. It was not an increase in monthly pension or a new government allowance.
Why is the 6% Interest Calculation important?
The judgment makes a distinction between the original incorrect payment and the later pension deductions.
The amount of ₹12,95,325 was the erroneous commutation payment credited in June 2024 and recovered in July 2024.
The 6% annual interest applies to the additional excess recoveries made after 31 July 2024, not automatically to the original ₹12,95,325.
The judgment does not provide a complete total of those subsequent deductions. Therefore, an exact interest amount cannot be calculated reliably from the published order alone.
For pensioners, this demonstrates the importance of establishing precisely which transactions are being disputed and when each recovery occurred.
How should pensioners check an unexpected recovery?
A pension deduction is not automatically wrongful. Some recoveries may be authorised under applicable pension rules.
However, when the same payment appears to have been recovered twice, pensioners should compare the underlying records.
Three checks are particularly important.
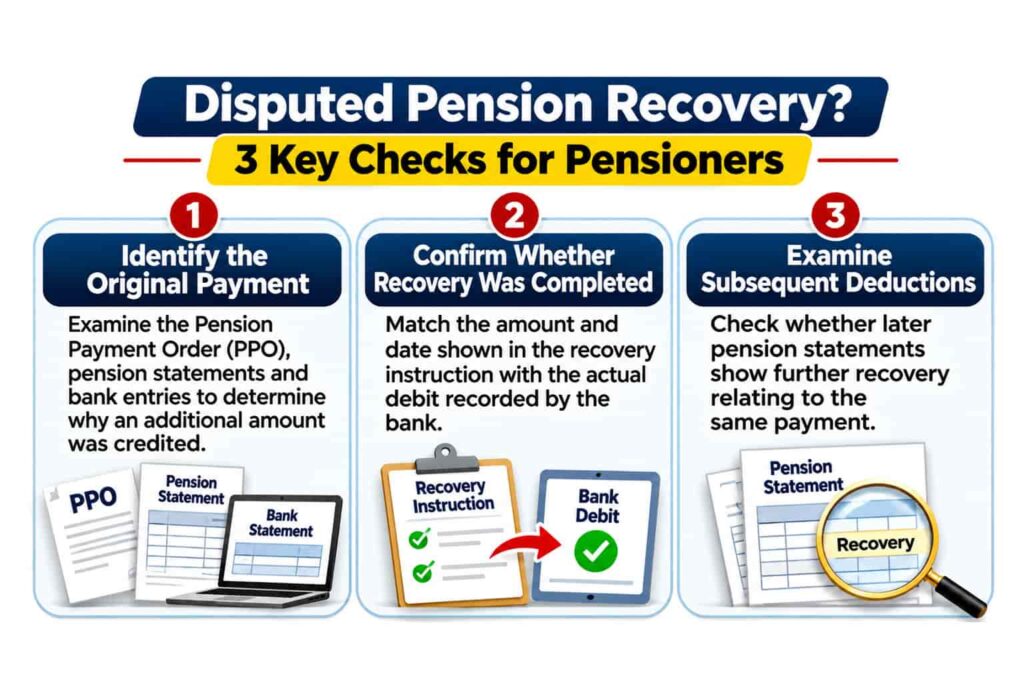
Which records should defence pensioners preserve?
For a disputed pension recovery, the following documents may be useful:
Pension Payment Order and relevant corrigenda
Monthly pension statements and bank account entries
SPARSH payment or recovery details, where applicable
Original recovery orders or adjustment communications
Emails, representations and grievance acknowledgements
Copies of replies received from the pension authorities
Pensioners should retain both the original documents and proof of submission of their complaints.
These records can help establish when an error was reported, what action was taken and whether the disputed amount has already been recovered.
Can every pensioner claim 6% interest and ₹25,000 compensation?
No. This decision relates to the circumstances of one retired Army Havildar.
The Tribunal considered the veteran’s prompt disclosure of the incorrect payment, the completed original recovery, the subsequent deductions and the litigation that followed.
The judgment does not create an automatic entitlement to interest or compensation for every pensioner facing a recovery dispute.
Other cases may involve different pension rules, circumstances and evidence.
Nevertheless, the decision provides a useful example of how an individual pensioner challenged additional deductions and obtained relief through the appropriate judicial process.
What does this judgment mean for SPARSH and defence pensioners?
The broader lesson is the importance of keeping pension records consistent across the bank, pension-disbursing agency and relevant pension administration system.
Where an overpayment has been recovered, subsequent pension deductions should be supported by an accurate accounting of the outstanding amount.
For affected pensioners, the practical approach is to obtain the recovery details, reconcile the transactions and raise a documented grievance through the applicable official channel.
If the matter remains unresolved, appropriate legal advice may help determine the remedies available.
The AFT Lucknow decision reinforces a straightforward principle: completing recovery of an erroneous payment and continuing to deduct money for that same payment are two materially different actions.
For pensioners facing unexplained deductions, accurate records and timely grievance reporting remain essential.
1. Armed Forces Tribunal, Regional Bench, Lucknow — Original Judgment
Case: Hav Sur Sari Charan (Retd.) vs Union of India & Others
O.A. No.: 546/2025
Judgment date: 27 October 2026
Read the Original Seven-Page AFT Judgment (PDF)
This is a hosted copy of the Tribunal judgment, not a direct download from the Tribunal’s official website.
2. Armed Forces Tribunal — Official Portal
Visit the Armed Forces Tribunal Website
3. SPARSH — Defence Pension Administration
Visit the Official SPARSH Portal
Disclaimer: This article explains the findings in O.A. No. 546/2025 and provides general information for pensioners. It does not constitute legal advice. The interest and compensatory costs awarded in this case are not universal pension benefits, and the outcome of other recovery disputes depends on their individual facts and applicable rules.
Leave a Reply